
















Financing the AI Buildout Beyond the Hyperscalers
Summary
- Most institutional capital for GPU deployments has gone to investment-grade deals, leaving the Compute Middle Market underserved.
- Smaller GPU financings carry more credit risk than investment-grade deals but are simpler to execute at the project level.
- Standardized structures could let smaller GPU financings reach the securitization market and lower their cost of capital.
The Financing Gap Below the Hyperscalers
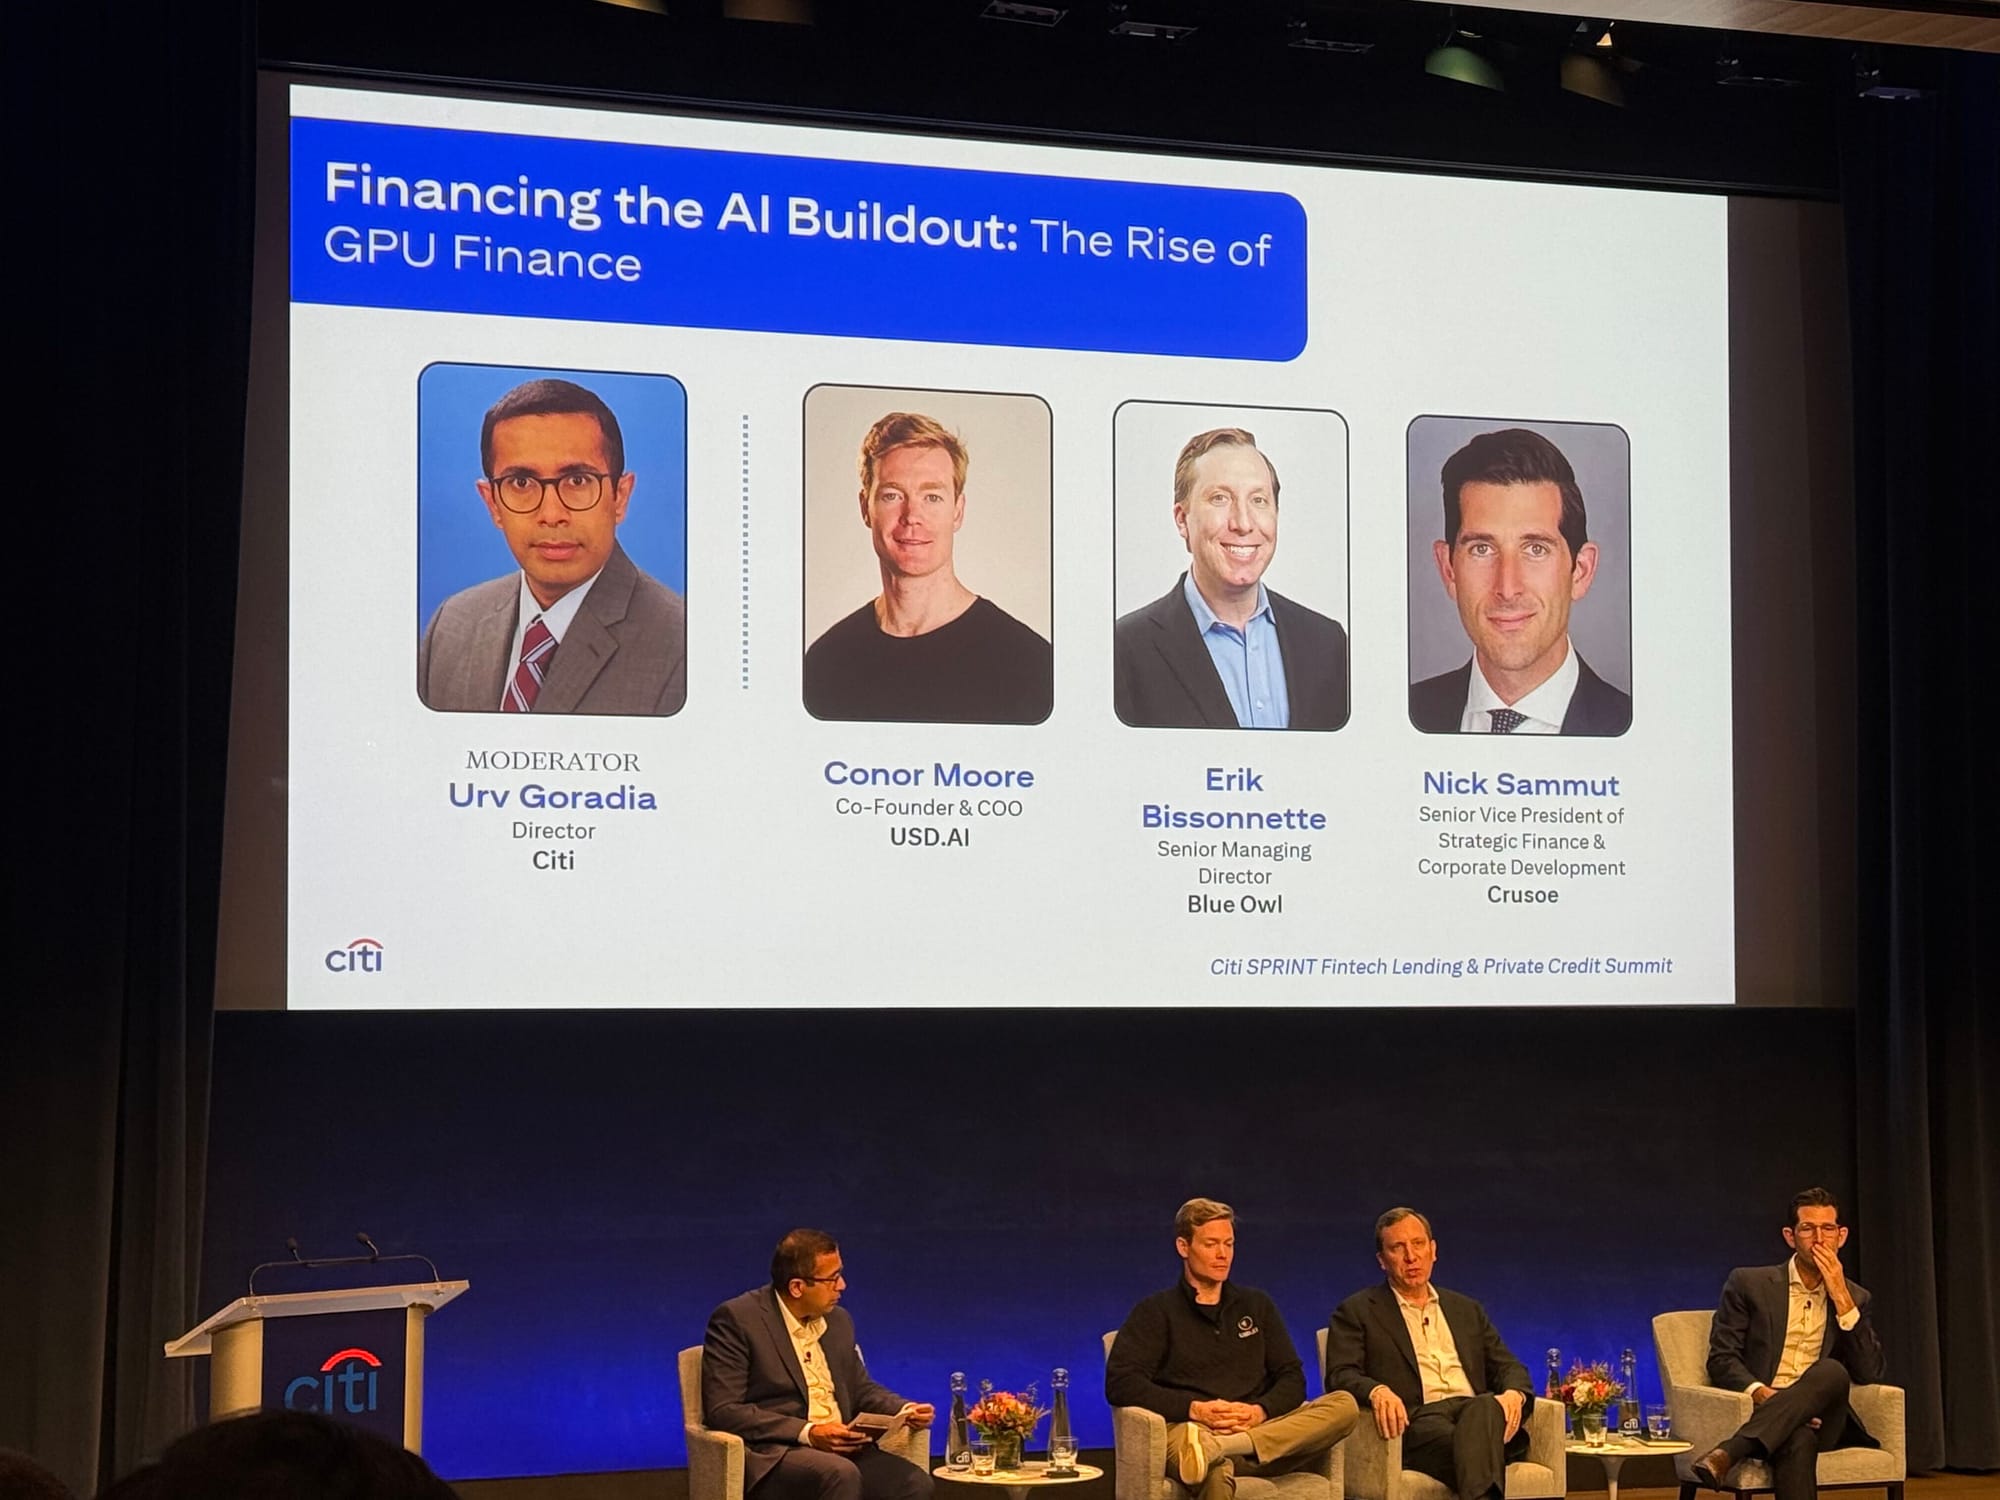
At the Citi SPRINT Fintech Lending & Private Credit Summit on November 10, USD.AI co-founder and COO Conor Moore joined Erik Bissonnette of Blue Owl and Nick Sammut of Crusoe for “Financing the AI Buildout: The Rise of GPU Finance.” Citi’s Urv Goradia moderated the panel.
Asked how big the market is, Moore pointed to estimates of roughly $5 trillion in AI infrastructure capex, about $2 trillion of it outside the hyperscalers. GPU sales tell a similar story: of the roughly $500 billion in GPUs NVIDIA sells each year, he estimated around $100 billion goes to buyers other than the hyperscalers.
Yet financing remains hard to come by in the Compute Middle Market. For an asset manager that can deploy $10 billion in one transaction, structuring dozens of $50 million deals for AI clouds takes far more work. That’s the gap USD.AI is working to close by standardizing GPU financings.
What Makes a Smaller GPU Deployment Financeable?
Large banks and asset managers already finance GPU deployments backed by long-term offtake contracts with investment-grade customers. Financing options thin out for GPU cloud operators and neoclouds serving younger or unrated companies. As Moore pointed out, established credit markets have ways to price that risk. GPU finance is still building that market.
Sammut described how Crusoe borrows from venture lending when assessing younger customers. Who backs the company? How much cash runway does it have? Does that runway cover the term of the offtake contract? He also drew a distinction between technological obsolescence and economic useful life. An older GPU can keep generating revenue after a new generation arrives, though what it earns may change over time.
Moore pointed to a trade-off lenders can assess at the project level. A borrower or its customers may carry more credit risk, while the deployment itself can be simpler to execute. In his example, a 1- to 10-megawatt project could go live roughly three months after a financing commitment, with much of the work coming down to shipping servers from the manufacturer and installing them on site.
Moore argued that this gap is where the opportunity lies. These financings aren’t priced like investment-grade deals, and in his view, what lenders are paid for more than anything else is the lack of education in the market. Lenders who put in the work to understand the asset can earn outsized returns.
How Lenders Assess GPU Risk
Bissonnette noted that neocloud equities had been volatile and their unsecured bonds had widened by 400 to 500 basis points, while pricing on GPU financings had moved only 50 to 75 basis points. He also pointed out that large lenders tend to favor long-term offtake contracts with investment-grade customers, while operators can earn more selling compute on the spot market when capacity is scarce. Those revenue profiles call for different financing structures.
For Moore, underwriting those differences starts with access to better data. Current purchase orders show what operators are paying for servers. Signed offtake contracts show what customers have agreed to pay for capacity. Both can be hard to see from outside the market, especially when hardware prices and demand are moving quickly. Moore cited all-in server prices, which rose roughly 50 to 75% between late 2025 and April 2026, a shift that was only visible to those seeing new purchase orders from manufacturers such as Supermicro.
How Smaller GPU Financings Could Reach More Capital
Moore expects power constraints, permitting and data privacy to create more room for smaller deployments. An inference provider may be able to use one or two megawatts at a former telecom colocation site, for example. As more deployments of that size come to market, the cost and effort of structuring each financing matter more.
Moore used the mortgage market to describe where GPU finance could go. A repeatable financing structure gives operators a clearer picture of what they need to secure financing and gives lenders a consistent way to evaluate collateral and deal protections. Over time, those financings could be pooled for securitization, giving institutional investors a way to finance many smaller deployments through a single transaction.
Conclusion
The panel agreed that demand for compute remains far ahead of supply, and that most institutional capital so far has gone to investment-grade deals. Moore’s case was that the Compute Middle Market is underserved because it is hard to read. Smaller GPU financings carry more credit risk but less project complexity, and the data that shows their unit economics sits with the operators and lenders active in the market. Standardizing these financings is how USD.AI aims to make them legible to more capital. USD.AI saw about $25 billion in prospective deals across 700 counterparties in the year before the panel. To finance your next deployment, talk to USD.AI.
FAQ
Why is financing harder to find for smaller GPU deployments?
Large asset managers can meet their mandates with a single $10 billion transaction, so $50 million deals get less attention. There is also little standardization around smaller financings, and many lenders lack data on demand and residual values. That leaves non-investment-grade borrowers with far fewer options than in other credit markets.
How does credit risk differ in a smaller GPU deployment?
Lenders typically take on more credit risk, since borrowers and their customers are often younger or unrated. In exchange, the project itself is simpler. Moore described a 1- to 10-megawatt deployment going live about three months after a financing commitment, with most of the work coming down to shipping and installing servers.
Why could GPU deployments get smaller over time?
Moore pointed to three forces: limited power in the US, tougher permitting and data privacy concerns among established businesses. As inference grows relative to training, operators may not need gigawatt campuses, and one- or two-megawatt sites, such as retrofitted telecom colocation facilities, become workable.
How could standardization lower the cost of GPU financing?
A repeatable structure tells borrowers what makes a project financeable and tells lenders what protections they get. Moore compared the endgame to mortgages, where standardized loans are pooled and securitized. If smaller GPU financings can reach the securitization market, he said, their cost should drop.